Purchase Plus Improvements

Lee Welbanks • May 17, 2023

The best place to start the mortgage process is with a pre-approval. But once you’ve been pre-approved for a mortgage and you’ve been shopping with location in mind, what happens when you can’t find a suitable property?


There's no doubt about it; finding the perfect property within your price range is a difficult task, especially for first-time homebuyers. So, before buyer’s fatigue sets in, maybe you should consider adding the cost of renovations into your purchase.


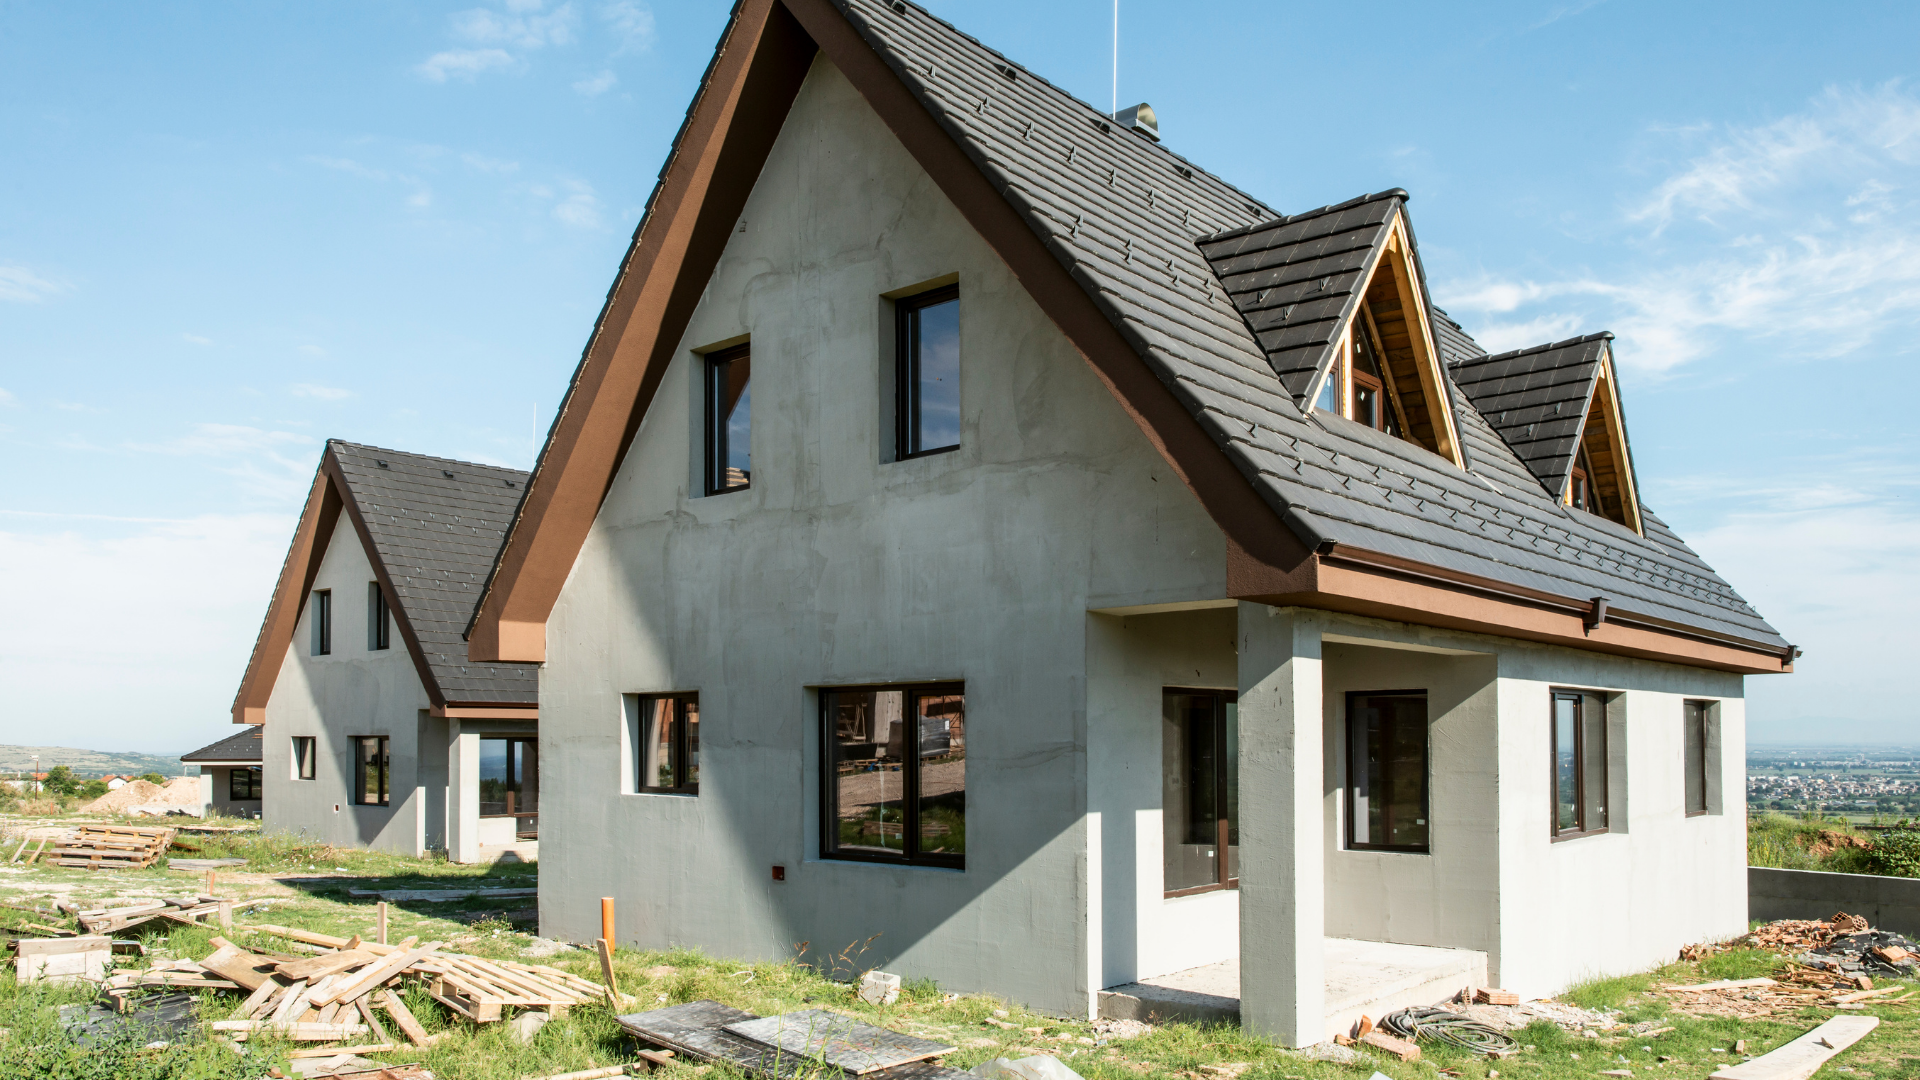
Buying a property and including the cost of renovations into the mortgage is available through a program called purchase plus improvements. When purchasing a home, you can add the cost of home upgrades into your mortgage, making it a great option if you can’t find something move-in ready and aren’t afraid to do a little work!


But while this sounds simple enough, in all honestly, it’s quite the process. There are some pretty strict rules to follow, but nothing that you can’t handle with the guidance of an independent mortgage professional.


Here’s a quick overview of the process. Firstly, you must provide quotes to the lender ahead of time for the work you would like to complete. It’s good to note that the renovations will have to increase the value of the property accordingly. From there, the lender doesn’t give you the money to do the upgrades; you have to come up with that yourself. However, once the work has been completed and verified by an appraiser, the lender will reimburse you and include the money in your mortgage.


This program isn’t for everyone. Buying a home is a stressful endeavour in and of itself. The added stress of having to undertake renovations right away might not be a good idea. But then again, if you have the financial wherewithal to handle the cost of renovations and like the idea of making it yours from the start, then this might be just the option you’ve been looking for!


Please connect directly; it would be a pleasure to walk through the exact process and outline what securing a purchase plus improvements would look like for you!
Lee Welbanks
By Lee Welbanks • October 7, 2026
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.
By Lee Welbanks • September 30, 2026
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.